SoFi Launches Interest-Bearing Digital Deposit
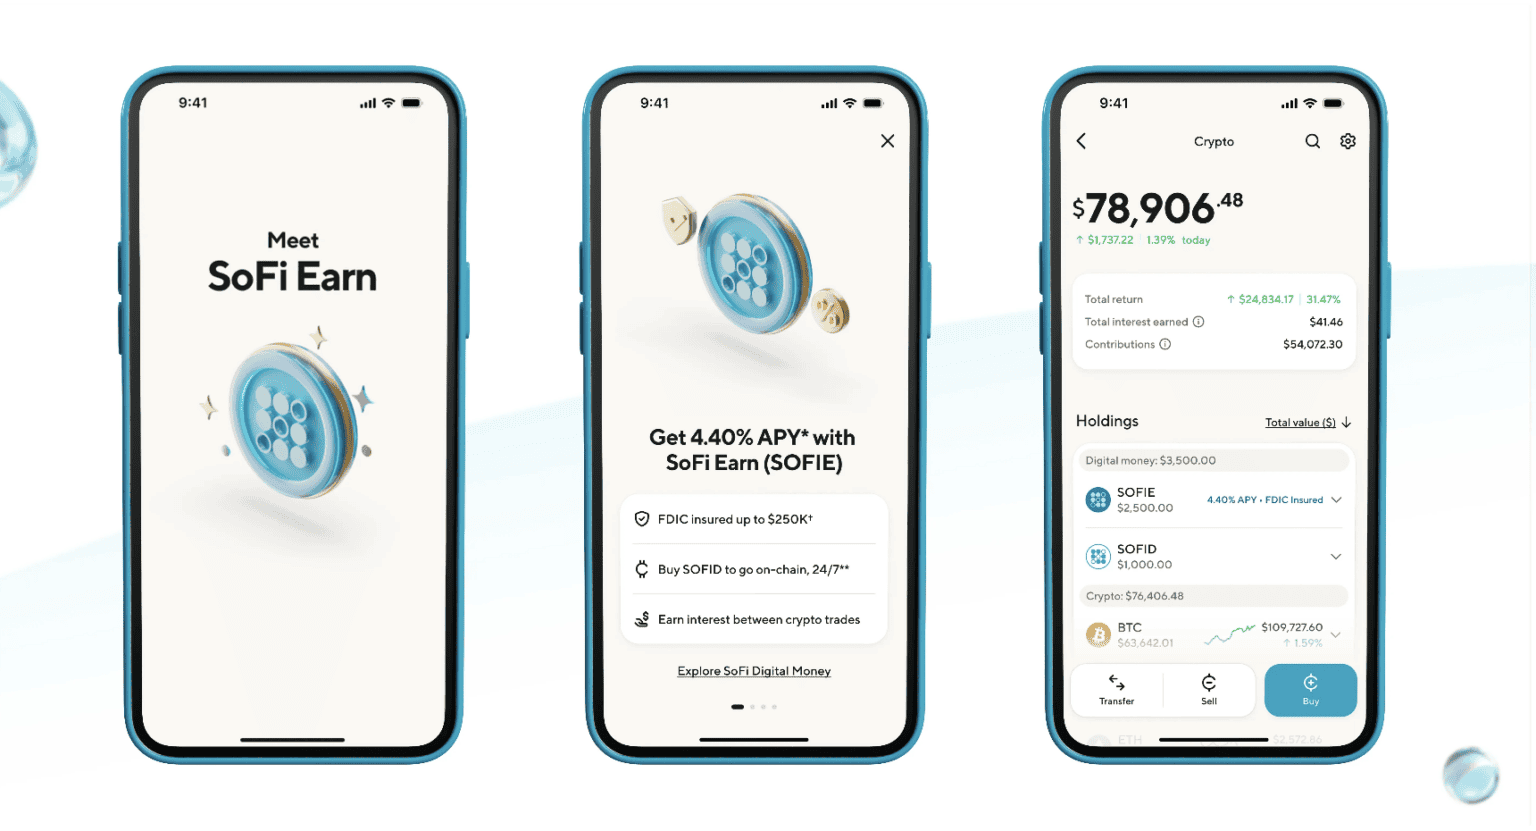
The digital bank rolled out SoFi Earn (SOFIE), a tokenized deposit product that pays consumers 4.40% APY while maintaining eligibility for FDIC insurance. The offering allows members to hold digital dollars that generate interest until they're ready to spend or transfer them.
Account holders can swap their SOFIE deposits for SoFiUSD stablecoins on a one-to-one basis whenever they want to buy cryptocurrency or move funds across blockchain networks. This structure lets customers earn returns on their digital dollars while preserving the option to use blockchain-based payment rails when needed.
Too much money in the digital asset ecosystem is sitting idle, leaving massive potential earnings on the table for millions of people, said CEO Anthony Noto. > We believe your money should keep working for you until the moment you need it.
Timing Follows OCC Stablecoin Yield Ban
The launch arrived within hours of the Office of the Comptroller of the Currency finalising regulations under the GENIUS Act, which prohibit stablecoin issuers from paying interest or yield to holders. The law takes effect January 18, 2027.
SoFi's tokenized deposit sidesteps those restrictions because it qualifies as a bank deposit rather than a payment stablecoin under the GENIUS Act's definitions. That distinction allows the company to offer interest-bearing digital dollars under existing banking rules while stablecoin issuers cannot.
Critics have noted the legislation leaves ambiguity around third-party reward programmes, raising questions about whether exchanges and other intermediaries can still offer yield on stablecoins through separate arrangements.
Expanding Digital Asset Platform
SOFIE marks SoFi's fifth crypto product in under a year. The company has steadily built out its digital asset infrastructure with consumer crypto trading, the SoFiUSD stablecoin, and Big Business Banking, a platform that lets companies manage fiat and digital assets from one regulated interface.
The rollout will reach all SoFi Crypto members by November, giving the bank a head start in the tokenized deposit market before the GENIUS Act restrictions take effect in early 2027.
Strategic Implications for Banks
The move raises questions about consumer behaviour in digital asset markets. If customers can earn interest on tokenized deposits and convert them to stablecoins on demand, there's little reason to park funds in non-yielding stablecoins long-term. SoFi's structure incentivises users to keep their tokenized deposits at the bank rather than holding assets elsewhere.
Traditional banks worried about deposit outflows to digital assets may find a roadmap in SoFi's approach. By linking interest-bearing deposits to stablecoin functionality, financial institutions can offer customers both yield and blockchain transaction flexibility without forcing a choice between the two.
This strategy could help banks retain deposits while still participating in blockchain-based payment ecosystems, especially as regulatory frameworks around stablecoins and tokenized assets continue to evolve.
Source
Original coverage by Finovate.
Use the button below to read the article on the publisher website.
Read on FinovateSusiję su šiuo straipsniu