
6 Step Sanctions Screening for Payments: Compliance Teams’ Checklist
Screen every payment, and every free-text field attached to it, against consolidated official sanctions lists (EU, UN, OFAC, UK) before you approve it. Lithuanian banks now clear roughly 98% of flagged payments within three days, so a hold is not a crisis. If you find a match or a red flag, hold the payment, request supporting documentation, and escalate to legal or compliance immediately.
TL;DR:
- Most flagged payments are cleared within three days, but manual review time increases significantly if clients delay providing supporting documentation.
- Screening against EU, UN, OFAC, and UK sanctions lists must be conducted sequentially, with cross-checks and escalation in case of discrepancies or partial matches.
- Red flags such as beneficiary name mismatches or routing through unfamiliar intermediaries require comprehensive document collection, timestamps, and rationales for suspicions.
- Automated, integrated sanctions checks within the payment process improves efficiency and reduces the likelihood of delays caused by missing context.
- Building continuous monitoring and structured metadata into payment infrastructure ensures scalable compliance without slowing cross-border transactions.
DemivoltBuild More Controlled Payment OperationsDemivolt provides compliant business banking infrastructure for managing cross-border payments, dedicated IBAN accounts, and business cards.Explore Demivolt
Table of Contents
- Sankcijų Patikra Mokėjimams: The Step-by-Step Payment Check
- Where Do You Check Payments Against Sanctions Lists?
- What Red Flags Trigger Enhanced Due Diligence?
- How to Build Sanctions Screening Into Payment Operations
- Why Payment Infrastructure and Sanctions Screening Belong Together
- Operationalize Sanctions Checks Without Slowing Down Payments
- Sources
- FAQ
Sankcijų Patikra Mokėjimams: The Step-by-Step Payment Check
A defensible sanctions decision comes from a sequence, not a gut call. Here is the order that holds up under audit.
- Verify structured identifiers. Confirm the IBAN, BIC/SWIFT code, and legal entity name against your KYC records. An exact-name mismatch between the payment instruction and your onboarding file is the first thing an auditor checks.
- Parse the unstructured fields. Payment purpose lines, “on behalf of” (OBO) notes, and invoice references often hide the real party to a transaction. Run fuzzy-name matching and check for transliterations, since a sanctioned individual’s name may appear in three different Latin-alphabet spellings depending on the source document.
- Check intermediaries and correspondent banks. A clean sender and a clean beneficiary do not guarantee a clean route. Screen every BIC code in the chain, including correspondent banks that never appear in the main payment instruction.
- Apply matching rules deliberately. Decide in advance what counts as an exact match versus a fuzzy match, and set a defined threshold for when a fuzzy hit goes to human review rather than automatic clearance.
- Decide and act. Three outcomes exist: proceed and document the clearance, request additional documents (invoice, contract, ultimate beneficial owner disclosure), or hold and escalate.
- Record everything. Log the decision, the timestamp, the reviewing officer, and the underlying evidence.
That last step matters more than most teams treat it. Lietuvos bankas points out that regulators expect financial institutions to re-check client data automatically whenever sanctions lists update, not just at onboarding. A screening record without a timestamp and a named reviewer is close to useless if a regulator asks you to reconstruct why a payment cleared six months ago.
Where Do You Check Payments Against Sanctions Lists?
No single database covers every sanctioned party worldwide, so checking one list and stopping there is a common and costly mistake. Four official sources form the backbone of any credible screening process:
- EU consolidated sanctions list — the canonical source for firms operating under EU law, updated through implementing acts and searchable by name, alias, and identifier.
- UN Security Council consolidated list — the primary reference for UN-level measures, which EU and national lists sometimes lag by days.
- OFAC sanctions search — the US portal, whose SDN and consolidated listings frequently extend broader than EU coverage, particularly for entities tied to specific sectors or jurisdictions.
- UK OFSI sanctions search — necessary for any payment touching UK counterparties or UK-cleared currency.
Each portal accepts name and identifier searches, but only some display entity relationships, such as ownership links to a listed party. That gap is exactly why a name-only search on one list is not enough.
Check in sequence: EU first for baseline legal coverage, then UN, then OFAC, then UK OFSI. If any two portals disagree, or a name returns a partial match with no clear resolution, escalate to your bank’s sanctions team or the relevant national authority before processing the payment.
What Red Flags Trigger Enhanced Due Diligence?
Some risk indicators are obvious. Others hide in plain sight inside routine paperwork, which is exactly why they catch experienced teams off guard.
Watch for these patterns:
- “On behalf of” (OBO) entries where the paying party and the beneficial party differ from the named account holder.
- Routing through unfamiliar intermediaries that add extra correspondent banks with no clear commercial reason.
- Beneficiary name mismatches between the payment instruction and the underlying invoice or contract.
- Sudden changes in payment terms, such as a long-standing counterparty suddenly requesting payment to a new account in a different jurisdiction.
- Routing through bridge jurisdictions known for facilitating onward transfers to sanctioned end-destinations.
Legal commentary from COBALT warns that a counterparty’s real beneficiary is often hidden behind directors, shareholders, or informal OBO instructions, which is precisely why document review has to go beyond the payment instruction itself.
When a red flag surfaces, request UBO disclosure, a certificate of origin, transport documents, translated corporate filings, and registry extracts proving the business relationship predates the transaction. Document every step with a timestamp and a written rationale for the decision.
Pro Tip: Build your EDD evidence file as you go, not after the fact. A compliance officer who can produce a dated request-and-response trail for every document defends a hold far more easily than one reconstructing the timeline weeks later.
How to Build Sanctions Screening Into Payment Operations
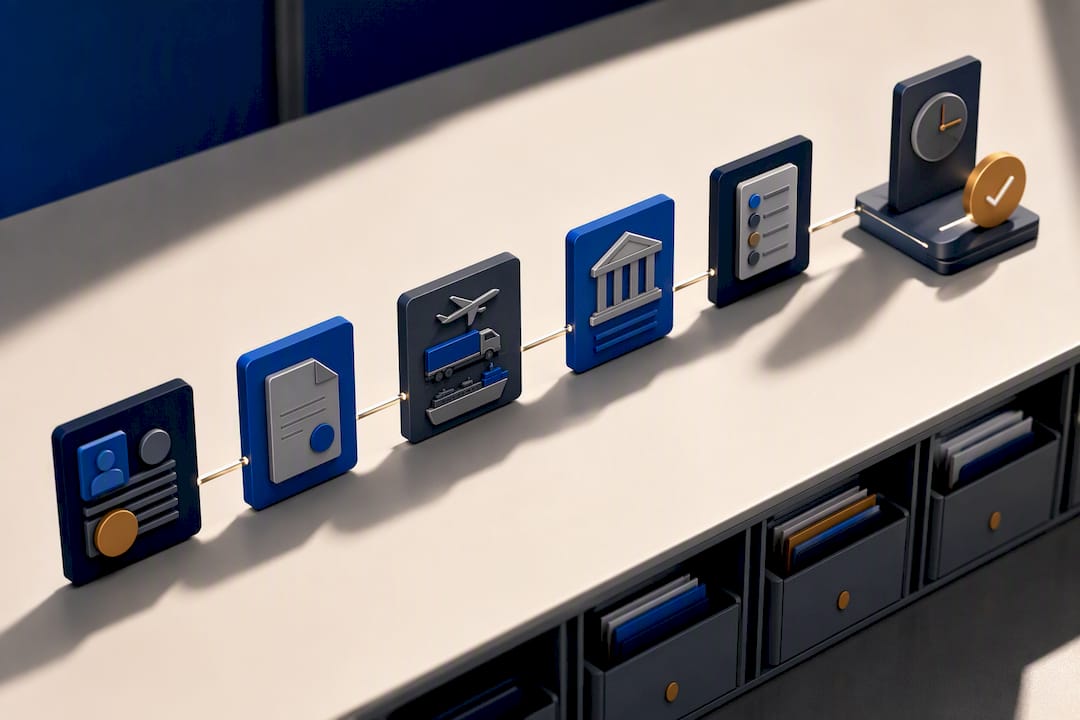
Manual, one-off checks do not scale once payment volume grows, and ad-hoc screening is increasingly the weak link regulators flag first. Here is how to fix that structurally.
- Centralize screening. Run one team or one platform responsible for checks at onboarding and again before every payment, rather than leaving it to whichever analyst processes the transaction that day.
- Add continuous monitoring for high-risk counterparties, since a name that cleared six months ago can appear on a list today.
- Parse free-text fields programmatically. Payment purpose and OBO notes should run through automated matching that flags probable hits for human review, rather than relying on a reviewer to spot them manually.
- Standardize templates for high-volume counterparties. Fewer free-text fields mean fewer ambiguous entries and fewer false triggers.
- Set internal SLAs. Triage within two hours of a flag, and reach a full EDD decision within 72 hours. Media coverage of Lithuanian banks’ improved processing times confirms that client responsiveness in supplying documentation is often the single biggest factor lengthening or shortening a hold.
- Route holds into a ticketing system connected to your payment initiation flow, so a flagged transaction never sits in someone’s inbox waiting to be noticed.
Teams that pair this structure with AI-assisted continuous monitoring tend to cut review time without loosening the standard, since the software handles volume and the analyst handles judgment.
Why Payment Infrastructure and Sanctions Screening Belong Together
Screening works best when it is built into the payment flow, not bolted onto it afterward. Structured metadata, captured at the point of payment initiation, and role-based approval controls both cut down the back-and-forth that stretches a routine hold into a multi-day investigation. A risk-based mix, automation for volume and human review for judgment calls, remains the only approach that scales without weakening the standard.
— dd
Operationalize Sanctions Checks Without Slowing Down Payments
Some payment infrastructures provide compliance teams with controls such as dedicated IBANs for cleaner reconciliation, role-based approvals to route flagged payments to the appropriate reviewer automatically, and SEPA and SWIFT processing with structured metadata captured at initiation rather than reconstructed after the fact.
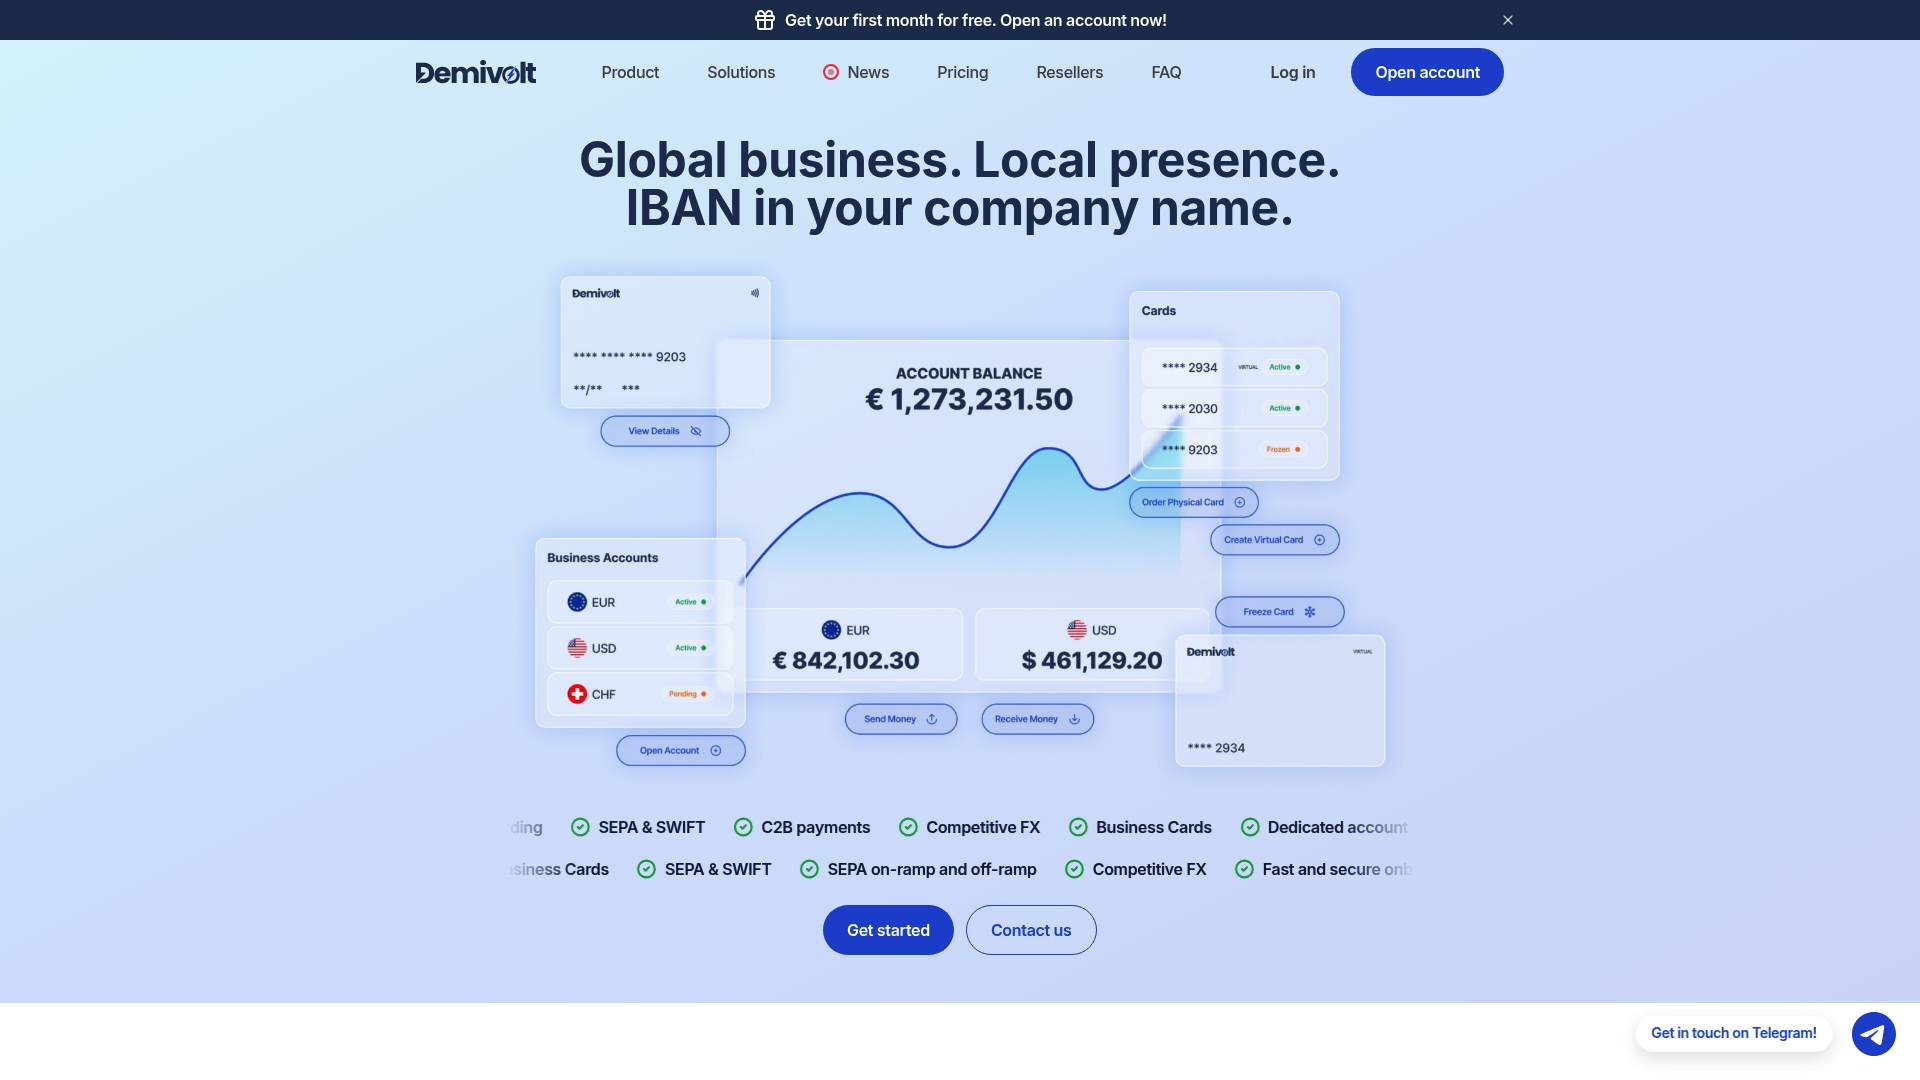
That structure matters because most of the friction in a sanctions hold comes from missing context, not the check itself. When your payment platform captures beneficiary details, purpose codes, and intermediary data cleanly at the point of transfer, your compliance team spends less time chasing documentation and more time making the actual risk call. Demivolt’s multi-account and role management setup supports exactly that workflow, and its payments infrastructure is built for cross-border operations where sanctions exposure is a daily reality, not an edge case. If your current setup makes every flagged payment a manual scramble, consider exploring compliant payment flow solutions to improve your process.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Lietuvos bankas: mokėjimų patikrinimų dėl sankcijų terminas trumpėja iki 3 dienų - Delfi verslas
- Implementation of international sanctions in financial institutions — Lietuvos bankas
- OFAC sanctions search
- UN Security Council consolidated list
- EU sanctions (restrictive measures) — European Commission
FAQ
What lists should I check for sanctions on a payment?
Check the EU consolidated list, the UN consolidated list, OFAC’s SDN list, and the UK OFSI list, in that order, for any cross-border payment. Cross-check across all four when a name returns a partial or ambiguous match on any single portal.
How long does a sanctions hold typically take?
In Lithuania, about 98% of flagged payments clear within three days, and most are eventually executed rather than blocked outright. Holds stretch longer mainly when the client is slow to provide requested documentation.
What counts as a false positive in sanctions screening?
A false positive is a name or entity that superficially matches a sanctions list entry but is not actually the sanctioned party, often due to a common name or a partial identifier overlap. Resolving it quickly requires comparing additional identifiers like date of birth, address, or registration number rather than relying on the name alone.
What documents should I request during enhanced due diligence?
Request ultimate beneficial owner disclosure, a certificate of origin, transport documents, translated corporate filings, and registry extracts confirming the business relationship. Document each request and response with a timestamp to support your compliance file if regulators later review the decision.
Can payment platforms automate sanctions screening?
Yes. Modern payment infrastructure can run automated checks against consolidated lists at both onboarding and pre-payment, and platforms like Demivolt build role-based approval and structured metadata capture directly into the payment flow to reduce manual review time. Full automation still requires human review for fuzzy matches and genuine red flags.